Another Nobel Peace Prize, a Russian Diesel Deal, and the Rising Tide of US Household Debt, Learn What the Stats Reveal

Digital Edition 2026  |  Volume 31

Hot Topic

A Nobel Peace Prize comes home…

South African human rights lawyer and judge Navanethem "Navi" Pillay has been awarded the 2026 Nobel Peace Prize, recognising a lifetime dedicated to defending human rights, strengthening international law and holding powerful individuals accountable.

But the significance of this year's award extends well beyond the remarkable career of its recipient. It comes at a time when international legal institutions are facing mounting political pressure, and when the principles underpinning the global rules-based order are increasingly being challenged.

Born in Durban in 1941, Pillay grew up under apartheid, experiencing firsthand the discrimination that would shape her career. In 1967, she established her own law firm, challenging racial injustice and defending anti-apartheid activists, including Nelson Mandela. She subsequently earned a doctorate from Harvard University before embarking on an extraordinary international legal career. Her achievements include serving as a judge at the International Criminal Tribunal for Rwanda, the International Criminal Court and, between 2008 and 2014, as the United Nations High Commissioner for Human Rights.

Among her most important contributions was helping establish that rape and sexual violence could constitute acts of genocide and crimes against humanity. Her work also advanced legal accountability for propaganda used to incite genocide, establishing precedents that continue to influence international criminal law. More recently, Pillay chaired a United Nations commission investigating the conflict in Gaza. The commission concluded that Israel had committed genocide against Palestinians, a finding firmly rejected by the Israeli government. She also serves as an ad hoc judge at the International Court of Justice in proceedings concerning allegations of genocide against Myanmar's Rohingya minority.

Unsurprisingly, the Nobel Committee's decision carries considerable geopolitical significance.

Announcing the award, committee chair Jørgen Watne Frydnes warned of a global shift towards power politics at the expense of established legal frameworks. The message was clear: international law must remain relevant even when its application proves politically inconvenient. That principle is increasingly contested. The United States has imposed sanctions on officials of the International Criminal Court, while several major powers have challenged the authority or jurisdiction of international legal institutions. Supporters regard these bodies as essential safeguards against impunity; critics question their jurisdiction, impartiality and implications for national sovereignty.

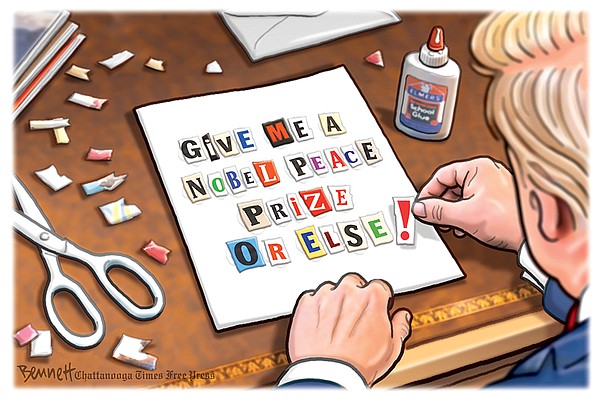
The award also attracted attention because US President Donald Trump had openly sought the Nobel Peace Prize. His disappointment subsequently became public, adding another political dimension to an already sensitive decision.

Yet Pillay's recognition ultimately raises a question considerably larger than any individual leader or conflict: Can international law retain its authority in a world increasingly shaped by geopolitical power? The answer matters beyond diplomacy. International legal frameworks underpin treaties, trade relationships, sovereign obligations and the broader predictability on which global economic cooperation depends. Their erosion would not necessarily produce immediate financial-market consequences, but it could contribute to a less predictable international environment.

For South Africa, Pillay's achievement is also a moment of national significance. From confronting apartheid in Durban to shaping international justice in The Hague, her career reflects the influence that South African legal figures have exercised far beyond the country's borders.

The Nobel Peace Prize cannot resolve the tensions confronting international law. Nor can it guarantee that powerful states will respect the institutions established to uphold it. But it does deliver a timely reminder: a world governed by agreed rules is fundamentally different from one governed solely by the interests of those powerful enough to impose their will. And preserving that distinction may prove one of the defining challenges of our time.
Stewart Dando

Stewart Dando

Director: attooh! Asset Consulting | SAIFM, ACISI

Squawk Editor in chief

The opinions and views expressed in this newsletter are those of the author and do not necessarily represent those of the attooh! Group or its affiliates. Content stated as fact was fact at the time of writing. The information in this newsletter is not intended to constitute financial advice as contemplated in the Financial Advisory and Intermediary Services Act.

Interesting Stuff

The week ahead: Signs of progress in negotiations or risks of escalatory strikes involving Iran, the US, and Gulf nations will continue to be closely monitored as high energy inflation keeps global bond yields near multi-decade highs.

Equity markets will also be shaped by corporate earnings, headlined by TSMC, ASML, JPMorgan Chase, Bank of America, Citigroup, Johnson & Johnson, LVMH, and UnitedHealth. On the economic calendar, US CPI and PPI prints will take the spotlight, alongside domestic retail sales, industrial production, and the terms of trade. In the eurozone, investors will look to upcoming industrial production and trade data.

Meanwhile, China's trade balance will draw attention amid persistent protectionist measures from key partners, and monetary aggregates will show the scale of credit for traditional and emerging economic sectors. Japan is set to release its PPI and machinery orders, while India and Australia are due to post labour market updates.

Under pressure: Dark clouds of growing financial pressure are gathering over South African households as we approach 2027, and employers need to look beyond traditional salary increases when considering how to support and retain employees. The hard-hitting fuel price increase on 7 October 2026 means an employee travelling approximately 100km per day in a vehicle using 12 litres per 100km could face roughly R610 more in monthly commuting costs, or more than R7 000 a year. The price of inland 95 unleaded petrol increased by R3.33 per litre to R30.25, while 93 petrol increased to R29.88. Diesel prices have also risen materially.

Employees are simultaneously facing rising medical aid, electricity, food and other household costs.

On 25 September 2026, the South African Reserve Bank increased the policy rate by 25 basis points to 7.25%, taking the prime lending rate to 10.75%. With the next MPC meeting scheduled for 19 November 2026, a further increase cannot be ruled out should inflationary pressures, particularly from rising fuel prices, persist.

Meanwhile, in Egypt: Egypt's annual urban inflation eased for the second straight month to 13.9% in September 2026 from 14.5% in August. It was the lowest inflation rate since February, as the impact of higher fuel prices continued to fade, with transport inflation slowing slightly to 24.3% in September from 24.4% in August, while housing and utilities inflation moderated to 35.2% from 42.8%.

Egypt raised fuel prices in early March by about 14% to 17% across a wide range of petroleum products, marking the first increase this year amid elevated global oil prices. Inflation also moderated for clothing and footwear (13.9% vs 14.0% in August), health (4.5% vs 4.6%), and alcoholic beverages and narcotics (8.3% vs 9.1%). Meanwhile, inflation accelerated for food and beverages (7.2% vs 6.3% in August) and furnishings (17.4% vs 16.9%). On a monthly basis, the CPI rose 1.3%, after edging up 0.1% in the previous month, marking the fastest increase in four months.

The Nobel Peace Prize cannot resolve the tensions confronting international law

The Week in the Media

Jargon of the week

What is the 'Time-Weighted Rate of Return (TWR)'?

The time-weighted rate of return (TWR) measures a portfolio's compound growth rate while excluding the impact of deposits and withdrawals. It breaks the investment period into smaller segments, evaluates performance for each, and then links them together to provide an accurate reflection of the portfolio manager's decisions.

This is a highly useful way to assess fund managers' performance, whether against other funds, benchmark indexes, or even different types of investments.

Source: Investopedia

Article of the week

Africa's new credit agency: why it's needed

The formal launch of the Africa Credit Rating Agency (AfCRA) has required considerable institutional commitment. It brings to fruition an effort that has been almost a decade in the making.

Read full article on Moneyweb →

Quote of the week

President Trump's decision to allow Russian diesel imports to the US runs directly counter to that law. — US Senate statement

President Donald Trump's diesel deal with Russian leader Vladimir Putin is facing bipartisan blowback in the US as lawmakers warn that the Trump administration is defying a federal law meant to crack down on Russia after the invasion of Ukraine.

In Conclusion

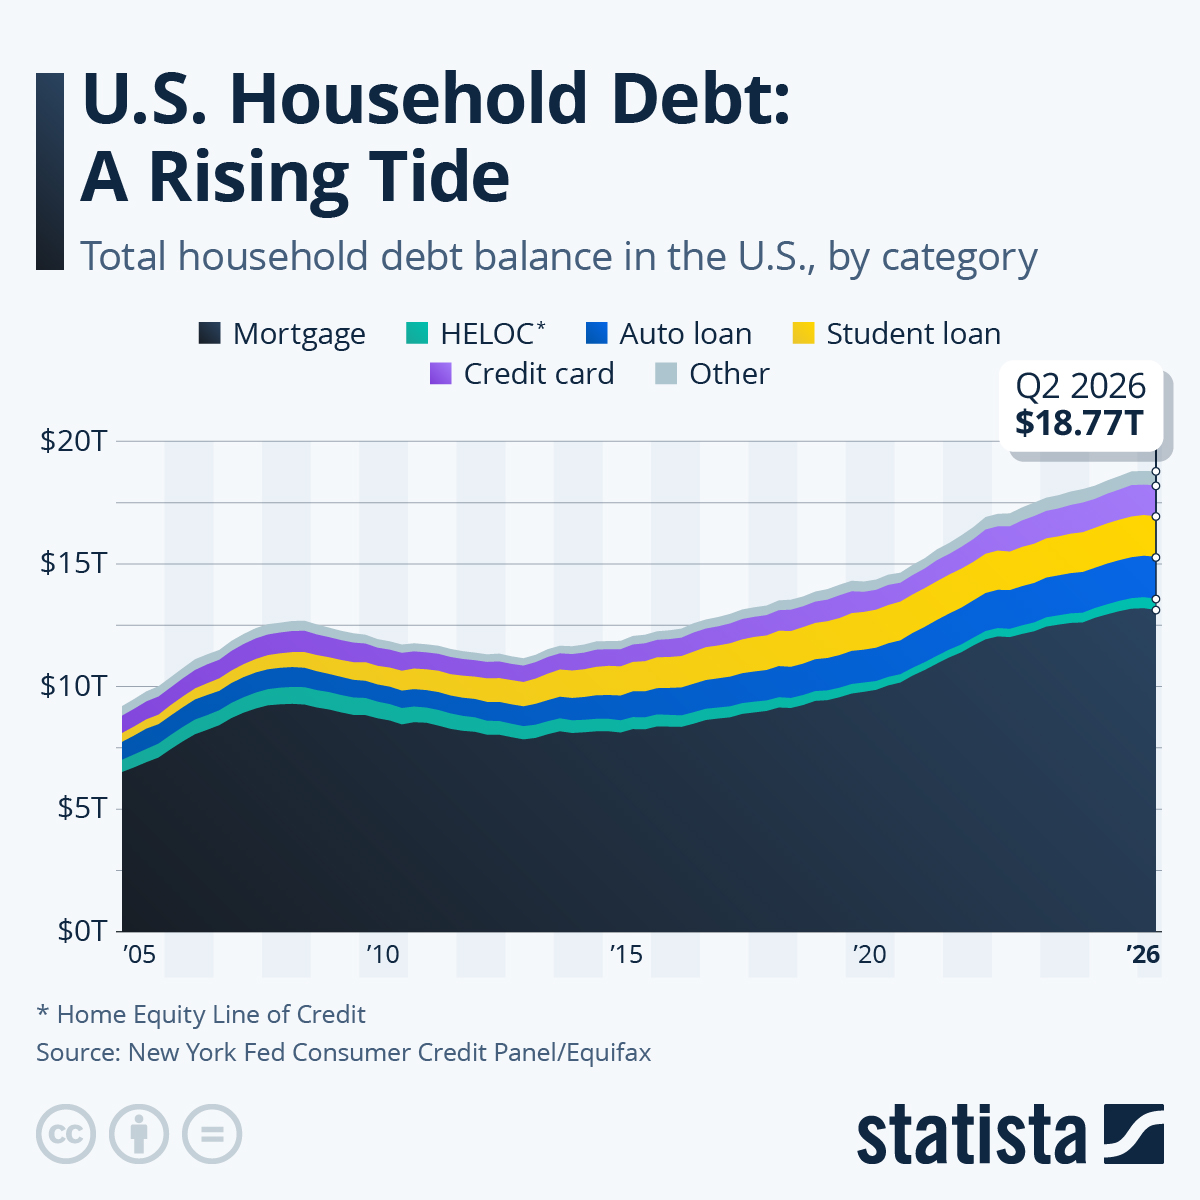
US household debt – A rising tide

According to the New York Fed's latest Quarterly Report on Household Debt and Credit, total household debt in the United States was virtually unchanged in the second quarter of 2026, decreasing by $13 billion – or less than 0.1% – to remain at $18.8 trillion. The decline – if we want to call it that – was the first since Q2 2020, when Covid lockdowns had resulted in a $76-billion drop in credit card debt, and a rare interruption in the near-constant rise of US consumer debt balances.

Despite the high level of debt, overall delinquency rates remain relatively low, though slightly elevated compared to the historic lows seen during the pandemic, when consumers were flush with cash from Covid stimulus checks. Looking at total consumer debt, 95.3% of the total balance was current (i.e. all payments made on time or less than 30 days late) at the end of Q2 2026, up from less than 90% in the midst of the financial crisis and from an average of 93.2% between 2010 and 2019.

U.S. Household Debt: A Rising Tide — Statista
Source: New York Fed Consumer Credit Panel/Equifax via Statista

Looking back to pre-pandemic debt levels, household debt grew $4.6 trillion or 33% since the end of 2019, mainly driven by a $3.6-trillion increase in mortgage debt. In 2020 and 2021, many households took advantage of historically low rates to refinance their mortgage and even take out some cash in the process. According to the New York Fed, 14 million mortgages were refinanced during the pandemic refinancing boom, during which home owners extracted $430 billion through cash-out refinances. As a result, mortgages account for 77% of the increase in total household debt since Q4 2019, followed by auto loans and credit card debt, which account for 8% and 7% of the total increase, respectively.

Cartoon of the Week
Cartoon of the week by Bennett, Chattanooga Times Free Press

© Bennett, Chattanooga Times Free Press (All Rights Reserved)
Printed/Used with permission.

The Squawk thanks the following sources of content and inspiration: Daily Maverick, Ninety One Asset Management, The Economist, Bloomberg, News24, Moneyweb, Financial Times, Investopedia, Reuters, Al Jazeera, Anchor Capital, FOX News, Morningstar, Bennett, Statista and ChatGPT5.

Monarch Minute
Marc Thomas

Marc Thomas

Head of Investments for attooh!

The Monarch Moderate Portfolio: a balance between stability and growth

Our previous article, The Monarch Moderate Conservative Portfolio: more growth than cash, but more volatility, looked at the second of the five risk categories. The Moderate portfolio sits in the middle of the range, and it is the one most investors picture when they think of a balanced investment: roughly half the portfolio working for growth, and the other half providing stability.

It targets a return of inflation plus 3% to 5% over a rolling five-year period, and is benchmarked against the average South African medium equity fund. At the end of August 2026 it held about 55% in equities, split fairly evenly between South African and global markets, with most of the balance in bonds and smaller allocations to property and cash. Around 37% is invested offshore, and it is managed within Regulation 28 limits.

The five-year horizon follows from that mix. An equity allocation of this size needs time to work: long enough to ride out a poor year or two, and long enough for compounding to deliver what income assets alone cannot. This is the portfolio for goals five years or more away, such as building capital ahead of retirement, funding a child's education, or long-term savings where growth matters but a steep fall would be unwelcome.

A look back at its performance over the last five years to the end of August 2026 highlights typical portfolio behaviour. The portfolio returned 10.45% a year, but not in a straight line. Its worst month in that period was a fall of just over 6%, and from peak to trough it was down 9.63% at its lowest. Past performance is no guide to the future, but the pattern is instructive: steady growth, interrupted occasionally by months of negative fluctuations.

Capital fluctuations measured in single-digit percentages are what you accept for the prospect of a return 3% to 5% above inflation over time, and it is that return which builds real wealth rather than simply preserving it. For money with five years or more to run, with moderate capital volatility, it is a sensible place to invest.

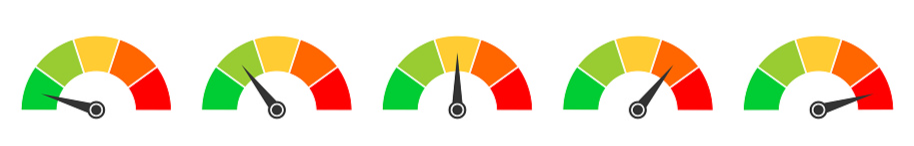
Monarch Moderate Portfolio — risk gauges across the model range